Four | Buy Now, Pay Later

Four | Buy Now, Pay Later
Four splits payments easily for budget conscious shoppers
Screenshots


Four | Buy Now, Pay Later – Flexible Payment Solution Overview
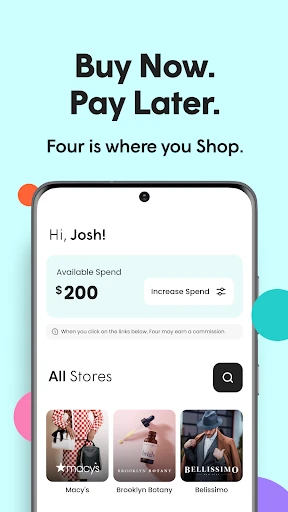
Four is a digital payment application that offers a Buy Now, Pay Later service, allowing users to split the cost of purchases into manageable installments. The app integrates with a wide range of online merchants and physical stores, providing instant credit decisions at checkout. Four aims to give users greater financial flexibility by deferring payment without incurring interest when paid on time. Its core functionality revolves around a simple approval process, transparent fee structures, and seamless repayment scheduling. The app is designed for both everyday shoppers and those managing irregular income, offering a modern alternative to traditional credit cards.
Chapter 1: Function
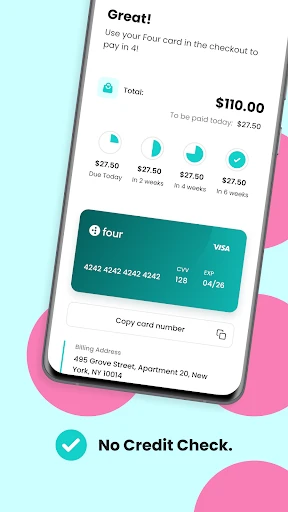
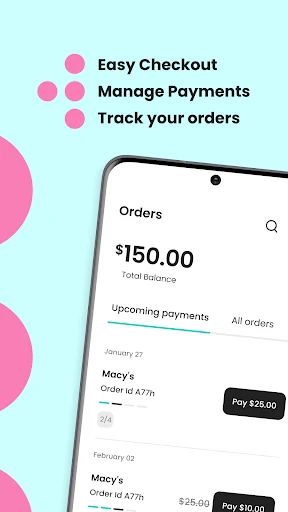
Four allows users to select a payment plan at the point of sale, typically dividing the total into four equal biweekly installments. The app requires a quick registration involving identity verification and linking a debit or credit card. Once approved, users receive a virtual card or can generate a one-time payment code for merchants. The repayment process is automated, with reminders sent before each due date. Users can track their spending, upcoming payments, and available credit limit within the app dashboard. Late fees are clearly communicated, and early repayment is allowed without penalty. Additionally, Four provides a dispute resolution feature for transactions, ensuring user protection. The app also supports multiple currencies and cross-border transactions for eligible users.
Chapter 2: Value
Fours primary value proposition is financial accessibility and budgeting control. Unlike traditional credit products, Four does not charge compound interest, making it a cost-effective borrowing option for short-term needs. The four-installment model aligns with typical biweekly pay cycles, helping users avoid overdrafts or high-interest debt. For merchants, Four increases conversion rates by reducing cart abandonment, as customers are more willing to complete purchases with deferred payment options. The app also fosters responsible spending by capping late fees and providing real-time balance alerts. From a user perspective, Four eliminates the need for a long credit history or high credit score, as approval is based on alternative data like transaction history and income stability. This inclusivity benefits young adults, freelancers, and gig economy workers who may lack traditional credit profiles. Furthermore, Four offers a grace period for missed payments before reporting to credit bureaus, giving users a safety net. The app also integrates budgeting tools that categorize spending, enabling users to track their overall financial health. By combining ease of use with transparent terms, Four positions itself as a ethical alternative to payday loans or high-APR credit cards.
Chapter 3: Scenarios
Fours target users include millennials and Gen Z shoppers who prefer flexible payment options but want to avoid revolving credit. Typical use cases include purchasing electronics, clothing, home goods, and travel bookings. For example, a student buying a laptop for online classes can split the 1,000 cost into four 250 payments, easing the immediate financial burden. A gig worker with irregular income can use Four to stock up on groceries or household essentials without depleting their bank account between projects. Small business owners may use the app to acquire inventory or software subscriptions with manageable installments. Additionally, Four is popular among travelers booking flights and hotels, as the app allows them to secure reservations while spreading costs over two months. Event tickets, gym memberships, and online courses are other common scenarios. The app also serves unbanked or underbanked individuals who lack access to traditional credit, enabling them to participate in e-commerce. For retailers, Four is integrated into point-of-sale systems for in-store purchases, such as furniture or car repairs. The apps versatility extends to subscription services, where users can pay for annual plans in installments rather than upfront.
Advantages
- instant credit approval without hard credit check
- splits payments into four bi-weekly installments
- works with most online retailers accepting Visa/MC
- no interest or fees if paid on time
- app tracks upcoming payment dates and balances
Disadvantages
- late fees apply after a missed installment
- requires linking a debit or credit card
- not available for all merchants or regions
- spending limit starts low for new users
- no grace period for payment delays
Frequently Asked Questions
Q: What is Four and how does it work?
A: Four is a Buy Now, Pay Later app that lets you split purchases into four interest-free installments. You select Four at checkout, pay 25% upfront, and the remaining balance is automatically charged every two weeks. No additional fees if paid on time. It integrates with online and in-store retailers via virtual card or merchant partnerships.
Q: Is Four free to use or are there hidden fees?
A: Four is free for users who pay on time. There are no interest charges, annual fees, or signup costs. Late payments incur a fixed fee of up to $8 per missed installment, depending on your region. No hidden charges exist beyond disclosed late fees. Always review the repayment schedule before confirming a purchase.
Q: Does Four require a credit check to sign up?
A: Four performs a soft credit inquiry during signup, which does not affect your credit score. Approval is based on factors like payment history with Four, transaction amount, and linked bank account status. No hard credit check is required, making it accessible to users with limited or no credit history.
Q: How can I use Four for in-store purchases?
A: For in-store purchases, generate a single-use virtual card within the Four app at checkout. The card is accepted anywhere contactless payments are supported. You pay the first 25% immediately via the virtual card, and Four charges your linked debit or credit card for the remaining installments every two weeks.
Q: Can I return items bought with Four and get refunded?
A: Yes, returns follow the merchant’s standard return policy. Once the merchant processes the refund, Four adjusts your payment plan accordingly. If you’ve already made payments beyond the first installment, the refund amount is returned to your original payment method within 5–10 business days. No additional fees apply. Contact Four support if the refund is not reflected after 14 days.
Technical Information
Recommended for You

Sydney Health
AP News: World & Local
Meeting - Video Meeting
Hushed: US Second Phone Number
Tarot!

PGA TOUR

NextLog
مانجا بلاير - Manga Player
Mastodon

Papercopy - Tracer

CEFCO Rewards

DailyWire+
OCEARCH Shark Tracker™

Room Temperature Thermometer
MAJORITY: Mobile banking
Babbel - Learn Languages

Offline Mp3 Player- uBand

Hue Light App Remote Control

Amazon Relay
Beauty Camera & Makeup Camera

Find Your Phone By Clap
Amazon Business: B2B Shopping
Lightsaber: Gun Sound Effects