Thrift Savings Plan
Thrift Savings Plan
Thrift Savings Plan for federal employees to save and invest for retirement
Screenshots
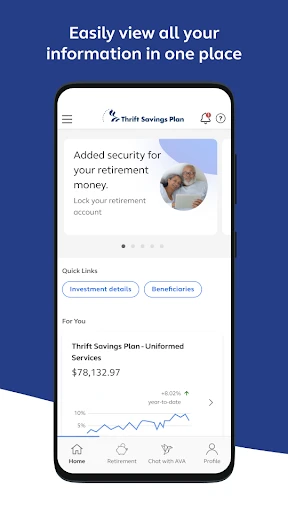
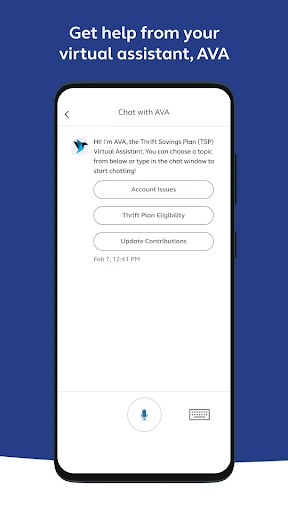
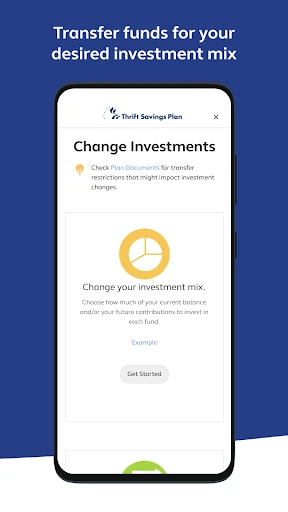
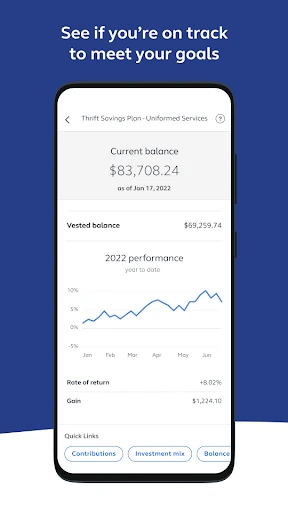
About Thrift Savings Plan feature
The Thrift Savings Plan (TSP) is a retirement savings and investment plan for federal employees and members of the uniformed services, including the Ready Reserve. It offers similar benefits to private sector 401(k) plans, providing a tax-advantaged way to save for retirement. The TSP is managed by the Federal Retirement Thrift Investment Board and features low administrative expenses, making it a cost-effective option for long-term savings. Participants can contribute a portion of their salary on a pre-tax or Roth (after-tax) basis, and receive matching contributions from their employing agency if eligible. The plan offers a selection of diversified investment funds, including government securities, fixed-income bonds, common stocks, and lifecycle funds that automatically adjust asset allocation based on the target retirement date.
Chapter 1: Function
The core function of the Thrift Savings Plan is to facilitate systematic retirement savings through payroll deductions. Participants can choose between traditional pre-tax contributions, which reduce current taxable income, or Roth contributions that allow for tax-free withdrawals in retirement. The plan automatically enrolls new eligible employees at a default contribution rate, though individuals can adjust their contribution percentage at any time. TSP offers five individual investment funds: the Government Securities Investment Fund (G Fund), Fixed Income Index Investment Fund (F Fund), Common Stock Index Investment Fund (C Fund), Small Capitalization Stock Index Investment Fund (S Fund), and International Stock Index Investment Fund (I Fund). Additionally, participants can select from ten lifecycle funds (L Funds) that automatically rebalance and become more conservative as the target date approaches. The platform also supports loan provisions, in-service withdrawals for financial hardship, and post-separation rollovers into other qualified retirement accounts.
Chapter 2: Value
The primary value proposition of the Thrift Savings Plan lies in its exceptionally low expense ratios, which are among the lowest in the retirement industry, often significantly below comparable 401(k) or IRA options. This cost efficiency directly enhances long-term compound returns by minimizing fee drag on participant balances. The plan provides unmatched simplicity through a limited but strategic fund lineup, reducing decision fatigue while maintaining broad market diversification across domestic equities, international equities, and fixed income. Automatic enrollment and escalation features help overcome inertia, encouraging higher savings rates over time. The Roth option offers valuable tax diversification, allowing participants to hedge against future tax rate changes. Loan features provide liquidity without credit checks or early withdrawal penalties, as long as repayment terms are met. For uniformed service members, the TSP integrates seamlessly with the Blended Retirement System, including automatic and matching contributions that vest immediately. Lifecycle funds simplify asset allocation for those who prefer a set-and-forget approach, rebalancing automatically to maintain appropriate risk levels. The plan also offers robust beneficiary protections and spousal rights for married participants, ensuring that survivor benefits are clearly defined. Finally, the TSP provides comprehensive withdrawal flexibility at separation or retirement, including partial withdrawals, full distributions, annuity purchases, and direct rollovers to IRAs or other employer plans, giving participants control over their distribution strategy.
Chapter 3: Scenarios
The Thrift Savings Plan primarily serves active federal civilian employees, postal workers, and members of the uniformed services including the Army, Navy, Air Force, Marine Corps, Coast Guard, and Reserve components. A typical use case involves a new federal employee who is automatically enrolled at a 3 percent contribution rate and then proactively increases contributions to maximize the agency matching contribution, which generally matches dollar-for-dollar on the first 3 percent of pay and fifty cents on the next 2 percent. Another common scenario is a career military service member who opts into the Blended Retirement System, contributing at least 5 percent of basic pay to receive full matching, while also deploying for extended periods and maintaining uninterrupted contributions through direct deposit in combat zones. A senior civilian employee nearing retirement might use the TSP to consolidate previous retirement accounts from prior private-sector employment via rollover, then allocate their balance into the L Income Fund for capital preservation. A reservist on intermittent orders can contribute during active duty periods and adjust allocations via the TSP website from any location. Finally, a retired federal annuitant may utilize TSP's partial withdrawal feature to cover a large expense like a home renovation, while leaving the remaining balance invested to generate continued growth.
Advantages
- federal retirement savings with low expense ratios
- automatic payroll deductions simplify consistent investing
- tax advantages for both traditional and Roth accounts
- L Funds offer age-based automatic asset allocation
- government matching contributions for eligible employees
Disadvantages
- limited to five core investment fund options
- no option for direct international stock exposure
- withdrawal rules are restrictive before age 59½
- online interface feels outdated with limited mobile features
- no ability to invest in individual stocks or ETFs
Frequently Asked Questions
Q: What is the Thrift Savings Plan app?
A: The Thrift Savings Plan (TSP) app is a secure mobile application for federal employees and military members to manage their retirement savings accounts. It allows users to view balances, change contribution amounts, adjust investment allocations, and process withdrawals. The app supports biometric login and provides access to account statements and transaction history. No additional equipment is required beyond a smartphone.
Q: Is the TSP app free to use?
A: Yes, the TSP app is free to download and use. There are no in-app purchases or subscription fees. However, users must have an active TSP account, which requires being a federal employee or military member enrolled in the TSP program. Standard mobile data or Wi-Fi charges from your service provider may apply.
Q: What devices and systems are supported?
A: The TSP app supports iOS and Android devices. For iOS, it requires version 13.0 or later; for Android, version 8.0 or later. It is optimized for smartphones and tablets. The app is available in the Apple App Store and Google Play Store. It does not support desktop or non-smartphone platforms.
Q: Does the app allow loan or withdrawal requests?
A: Yes, the app enables users to request loans and withdrawals directly, including general purpose loans, primary residence loans, and age-based or hardship withdrawals. Users must follow the on-screen authentication steps and confirm eligibility. Processing times vary but are typically completed within a few business days. Some actions may require additional verification via the TSP website or phone.
Q: How can I resolve login issues in the app?
A: For login issues, first ensure you have a valid TSP account and are using the correct username and password. If you forget your credentials, use the 'Forgot Username' or 'Forgot Password' options on the login screen. The app supports multifactor authentication via text or email. If problems persist, contact the ThriftLine at 1-877-968-3778 or use the 'Contact Us' section in the app. The app does not support third-party password managers.
Technical Information
Recommended for You

clickworker
Opera GX: Gaming Browser

Fotor - AI Photo Editor

Paramedic Protocol Provider
Prepware Remote Pilot

Brightspace Pulse

Omada

Healofy Pregnancy & Parenting

Learn to Read - Duolingo ABC
Minute Money
Live weather: Forecast, widget
Color Genie
My Verisure

Glitter Beauty Coloring Pages
Protection 360™
Volume Bass Booster, Equalizer
Surveys On The Go
US Public Lands
جاباما | اجاره ویلا و اقامتگاه

Neon Clock Wallpaper
The Bible in pictures
Video Downloader

Locate Mobile by Number
